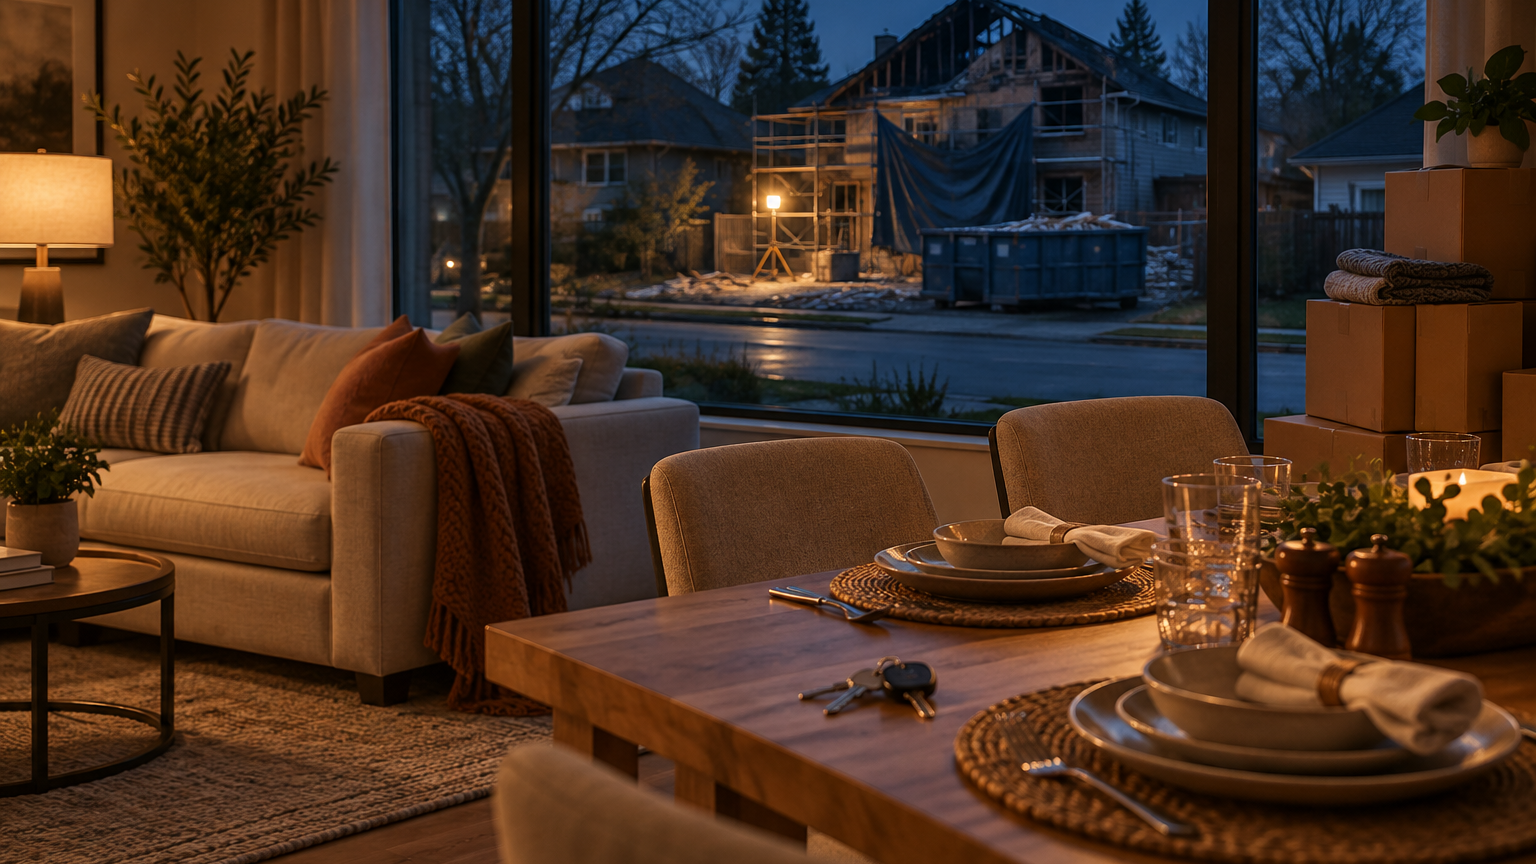
Insurance relocation housing and travel nurse housing are both 30-plus-day mid-term rental demand, but they are not the same business. A travel nurse books your unit for a contract she already knows the length of. A displaced homeowner moves in because a fire or a burst pipe made her house uninhabitable, her carrier is paying the rent under the additional living expenses part of her policy, and nobody — not her, not the adjuster, not you — knows on move-in day whether she leaves in six weeks or fourteen months.
That single difference changes how you price the unit, how you write the lease, and whether the placement is worth taking at all.
This is an operator's decision process for insurance-placement demand: what the money actually is, what the open-ended timeline costs you, and the four tests a unit has to pass before you put it on a placement firm's roster.
What insurance relocation housing actually is
When a covered loss makes a home unlivable, a standard homeowners policy pays additional living expenses — ALE. The Texas Department of Insurance describes it plainly: ALE covers rent, food, and other costs the household would not have if it were still at home (TDI).
Two things in that definition matter to you as the housing provider.
First, the rent is paid by or on behalf of the carrier, not out of a household budget. Second, ALE is capped. TDI notes ALE "might be limited to 10 to 20% of the amount of the dwelling coverage" on the policy, and a household that hits the cap before repairs finish pays the rest itself.
Carriers rarely hunt for rentals themselves. They use temporary-housing placement firms. CRS Temporary Housing, for example, works with insurance companies to house policyholders whose homes are uninhabitable and says it is "actively seeking property owners who are open to hosting short-term leases, typically spanning from 1 to 12 months" (CRS).
You are not marketing to the displaced family. You are getting your unit into a placement firm's inventory so the firm's team calls you when a loss happens in your market.
The three mid-term demand types, side by side
Most operators lump all 30-plus-day stays together and then get surprised. They behave differently:
Demand type | Who pays | Typical length | Length known at move-in | How you get it |
|---|
Travel medical | Traveler, sometimes an agency stipend | Tied to the assignment contract | Yes | Listing platforms, repeat referrals |
Corporate / relocation | Employer or relocation firm | Project or onboarding window | Usually | Direct B2B outreach |
Insurance placement (ALE) | Carrier, via a placement firm | 1 to 12 months per CRS's own range | No | Registered on a placement firm's roster |
The column that should change your behavior is "length known at move-in." Insurance placement is the only one of the three where the end date is a moving target from day one, because it tracks a construction schedule, not a calendar.
Why the open-ended timeline is the whole risk
Every other part of this looks attractive: a payer with money, a family that needs a full kitchen instead of a hotel, a lease length that clears most 30-day regulatory thresholds. The unknown end date is where operators get hurt, in three ways.
Repairs run long, then ALE runs out. If the household exhausts the ALE limit while the contractor is still working, the payer relationship changes mid-stay from carrier-funded to family-funded. That is a different credit conversation than the one you signed up for.
Repairs finish early. Your unit comes back to you in the middle of a month you assumed was booked, often with little notice, and you have no nightly calendar built out because you took the unit off the platforms.
The stay crosses a tenancy line. In many jurisdictions, an occupancy past a certain length starts looking like a tenancy with eviction protections rather than a guest stay. Where that line sits and what it triggers is state and city specific, and it is a question for a local real estate attorney before your first placement, not after an overstay.
The four tests before you list a unit for placement
Run these in order. A no on any of them means this unit is not the one to start with.
1. Can you carry the unit at the placement rent for the full window?
Model the unit at the monthly rate a placement firm would plausibly pay, not at your best nightly month. If the unit only clears its costs during peak season, a twelve-month insurance placement locks you into the shoulder months at the same rate.
2. Is your market a loss market?
Placement demand follows covered losses: fires, storms, water damage, and the occasional catastrophe event. A market with heavy weather exposure and dense single-family housing produces steady placement need. A market with none of that may put your listing in a queue for calls that never come.
3. Can the unit house a household, not a traveler?
Displaced families arrive with children, pets, and sometimes a household's worth of salvaged belongings. Parking, storage, laundry, a real dining table and a school district matter more than a photogenic desk nook.
4. Does your insurance follow the use?
A unit moving from nightly short-term stays to a 30-plus-day occupancy may fall outside the policy form you bought for short-term rental use. Confirm the change in writing with your carrier or broker before the first placement — read our breakdown of what STR policies do and don't cover and then take the specific question to your agent.
How to get on a placement roster
The mechanics are unglamorous, which is why most operators skip them.
Register the property directly with placement firms. CRS runs a landlord survey and then an optional paid step: "Preferred Providers appear at the top of our placement team's search results, carry a verified badge, and are contacted first when we source housing in their market," with enrollment for an annual fee (CRS).
Answer the phone the same day. Placement teams are solving a housing emergency inside a claim deadline. Availability confirmed in an hour beats a nicer unit confirmed tomorrow.
Keep a current unit sheet. Address, bedrooms, bathrooms, furnished or unfurnished, pet policy, parking, monthly rate, earliest move-in. One page, ready to send.
Decide your extension policy before you need it. Month-to-month after the initial term, at what rate, with how many days' notice. Extensions are normal in this channel; improvising them is not.
Register more than one firm. CRS is one placement company among several that serve carriers nationally. A single roster is a single point of failure.
Pricing: the two numbers that decide it
Insurance placement pays a monthly rate. Your nightly business earns a variable monthly total. Compare them on your own trailing numbers, not on a best month.
Line | Nightly operation | Insurance placement |
|---|
Gross revenue | Nightly rate × occupied nights | Fixed monthly rent |
Turnover cleans | One per stay | One at move-out |
Platform fees | Charged per booking | None on a direct lease |
Utilities | Yours, uncapped by guest behavior | Negotiable: yours, the household's, or capped |
Vacancy risk | Between every booking | Concentrated at the unknown end date |
Revenue certainty | Low per month, higher in peak | High per month, uncertain in duration |
Two rules keep this comparison from lying to you.
Use a trailing twelve-month average of your nightly net, not your July. And decide who pays utilities in the lease — an open-ended utility obligation on a family of five in a cold January is a real cost, not a rounding error.
If the monthly placement rate beats your trailing nightly net and the unit passes the four tests, the placement is the better business. If it only beats a below-average month, you are trading your upside for calm.
What to write into the lease
The lease is where this channel is won or lost, because the unknown end date has to be handled in writing rather than in a phone call three months in.
Payer of record. Name who pays and who guarantees payment if the placement firm's role ends mid-stay.
Initial term plus extensions. A stated initial term, then month-to-month, with a fixed notice period both ways.
Early termination. What notice you get when repairs finish ahead of schedule, and whether any part of the month is retained.
Utilities. Included with a monthly cap, or billed through — pick one and put the number in the document.
Occupancy and pets. Displaced households arrive as households; agree the headcount and pet terms before move-in, not after.
Condition and inventory. A dated photo inventory at move-in protects both sides on a stay that may run a year.
Have a local real estate attorney review the form once. You will reuse it for every placement after that.
Where this fits next to your other 30-day demand
You do not have to choose one channel forever. Operators who already run travel nurse and medical mid-term stays have most of the operating pieces in place: furnished units, monthly leases, a cleaner who works around long stays.
Insurance placement is an additional source of the same 30-plus-day demand, with a different payer and a different timeline risk. Treat it as a second lane on a road you already drive, and keep your direct booking channel alive so that when a placement ends early you have somewhere to send the calendar.
If you want a second set of eyes on whether your unit and market fit this channel, book a free diagnostic call.
FAQ
Who pays the rent on an insurance relocation placement?
The rent is funded through the policyholder's additional living expenses coverage, typically administered by a temporary-housing placement firm on the carrier's behalf. Confirm in writing who the payer of record on your lease is before move-in.
How long do these stays last?
CRS describes the leases it sources as typically one to twelve months. The end date tracks the repair schedule on the damaged home, so treat any stated length as an estimate and write extension terms into the lease.
What happens if the family's ALE coverage runs out?
TDI notes that a household that reaches its ALE dollar limit before repairs are complete pays the remaining costs out of pocket. Know in advance whether your lease lets you convert to a direct household-paid tenancy, end the term, or require an extension approval from the placement firm.
Does a 30-plus-day stay create tenancy rights?
It can, depending on state and local law and how the occupancy is documented. This varies too much to answer generally — have a local real estate attorney review your lease form before your first placement.
Do I need to furnish the unit?
Not always. CRS and similar firms source both furnished and unfurnished homes, since a displaced household may still have salvageable furniture. Ask each placement firm what their carriers request in your market.
Is it worth paying for a preferred-provider listing?
Only after you have confirmed that losses actually happen in your market and that your unit matches the household profile placement teams are asked to fill. Pay for priority placement in a market with demand, not for visibility in one without it.
Sources
Texas Department of Insurance, "Homeowners insurance guide" — additional living expenses definition and the 10 to 20% of dwelling coverage limit: https://www.tdi.texas.gov/pubs/consumer/cb025.html
CRS Temporary Housing, "Landlords" — lease lengths of one to twelve months, Preferred Housing Provider enrollment and annual fee: https://crsth.com/landlords/